The short answer
Between 2027 and 2031, marketing in MENA and the GCC will be shaped less by any single channel and more by where people discover, decide and pay. Five shifts do most of the work:
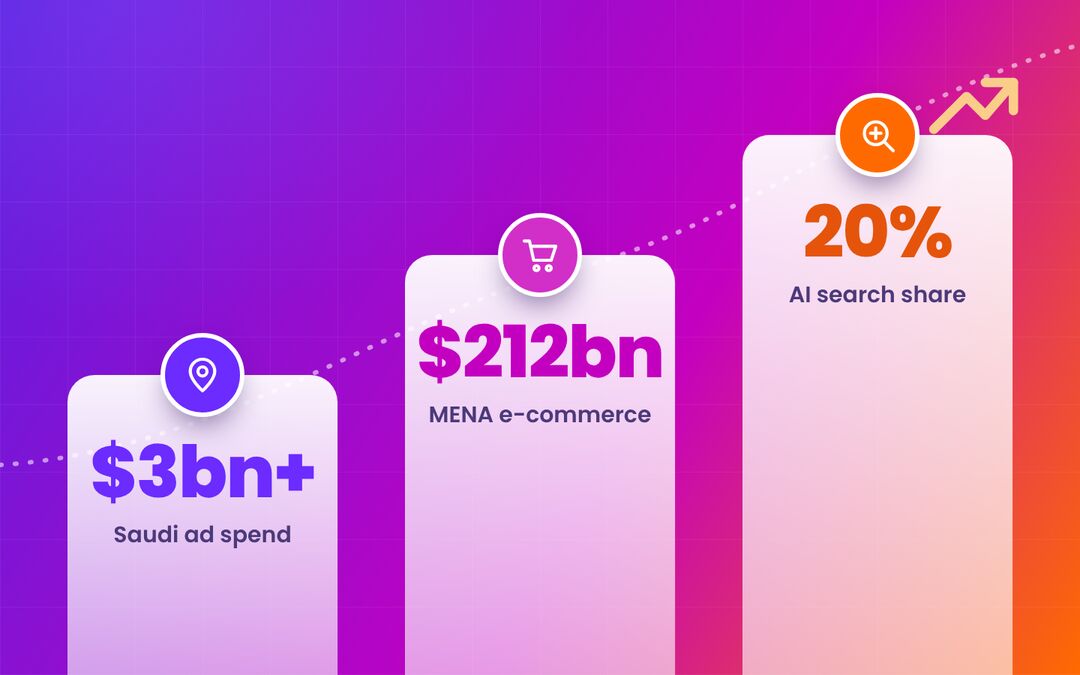
- Saudi Arabia becomes one of the most digital ad markets in the world. About 90% of Saudi ad spend is forecast to be digital by 2029, rising to 91% by 2030 (Gmedia / Oxford Business Group).
- Commerce media grows faster than any other channel. MENA commerce and retail media is forecast at $636m in 2026, up 22.2%, and above $700m by 2028, catching up with total TV (WPP Media).
- Search turns into answers. Generative search is forecast to grow from 1% of MENA search-and-intelligence ad revenue in 2026 to 20% by 2031 (WPP Media). Google's AI Mode already has more than 1bn monthly users.
- Checkout moves into the feed, the chat and the delivery app. 96% of UAE shoppers expect most online purchases to happen through social by 2030 (DHL).
- The calendar gets denser and earlier. Ramadan moves about 11 days earlier every year, from around 8 February in 2027 to early January in 2030. It will meet the AFC Asian Cup, Expo 2030 Riyadh and, in 2034, the FIFA World Cup.
The rest of this outlook sets out the numbers behind each shift, region by region and channel by channel, and what a brand can do about them in 2027.
Who this is for: marketing, growth and commercial leaders planning 2027 budgets across the UAE, Saudi Arabia, the wider GCC and India.
25 numbers for 2027 to 2031 at a glance
Every figure below is a published forecast or target, sorted by area. Sources are linked in the full sections and listed at the end.
| Area | Number | Year | Market | Source |
|---|---|---|---|---|
| Ad spend | More than $3bn total ad spend | 2027 | Saudi Arabia | WARC via AGBI |
| Ad spend | $2.7bn total ad spend | 2027 | UAE | WARC via AGBI |
| Ad spend | 90% of ad spend digital | 2029 | Saudi Arabia | Gmedia / OBG |
| Ad spend | Ad market growing 7 to 9% a year | to 2030 | MENA | Communicate Online |
| Ad spend | Advertising 51% of a ~$18bn media and entertainment market | 2028 | MENA | PwC Strategy& |
| Ad spend | Internet advertising $14.3bn | 2030 | India | PwC India |
| Channels | Commerce and retail media above $700m | 2028 | MENA | WPP Media |
| Channels | Streaming 55% of TV ad revenue | 2030 | MENA | WPP Media |
| Channels | Digital 49% of out-of-home | 2030 | MENA | WPP Media |
| Channels | Generative search 20% of search-and-intelligence ad revenue | 2031 | MENA | WPP Media |
| Channels | Ad-tech market SAR 312m ($83m), growing 20.7% a year | 2030 | Saudi Arabia | Gmedia / OBG |
| E-commerce | E-commerce $212.2bn | 2029 | MENA | Euromonitor via EZDubai |
| E-commerce | E-commerce above $13.8bn | 2029 | UAE | Euromonitor via EZDubai |
| E-commerce | 46% of retail payments online | 2030 | Saudi Arabia | Visa |
| E-commerce | Food delivery $26bn | 2030 | GCC | Redseer |
| E-commerce | 96% of shoppers expect most online buying via social | 2030 | UAE | DHL |
| E-commerce | Buy now, pay later $27bn to $53bn | 2030 | Saudi Arabia | Redseer |
| AI | $15tn of B2B purchases handled by AI agents | 2028 | Global | Gartner |
| AI | AI worth 12.4% of GDP ($135.2bn) | 2030 | Saudi Arabia | PwC |
| Creators | Creator economy $480bn | 2027 | Global | Goldman Sachs |
| Creators | Influencer marketing $771.6m | 2032 | GCC | PS Market Research |
| Demand | 150m visitors a year | 2030 | Saudi Arabia | Ministry of Tourism |
| Demand | Sports market $22.4bn | 2030 | Saudi Arabia | SURJ / PIF |
| Demand | Real estate transactions AED 1tn a year | 2033 | Dubai | Dubai Land Department |
How big will MENA and GCC advertising be by 2030?
The short answer is a market growing roughly 7 to 9% a year to 2030, led by Saudi Arabia, and close to entirely digital in its biggest market. WPP Media forecasts MENA advertising at $8.4bn in 2026, up 7%, after $7.7bn in 2025. A broader estimate, which includes more digital spend, puts the region nearer $11bn, growing 7 to 9% a year to 2030.
| Market | Latest actual | 2027 to 2030 outlook | Source |
|---|---|---|---|
| Saudi Arabia | $2.4bn to $2.5bn (2025) | More than $3bn by 2027; 90% digital by 2029, 91% by 2030 | WARC via AGBI, Gmedia |
| UAE | $2.15bn (2025) | $2.7bn by 2027, with digital growing more than 10% a year | WARC via AGBI |
| GCC | $5.1bn (2025) | About $5.5bn in 2027 even in a cautious scenario | WARC via AGBI |
| MENA media and entertainment | Digital 71% of revenue | Advertising 51% of an ~$18bn market by 2028, digital 74% | PwC Strategy& |
| India | Digital ~68% of ad spend (2026) | Internet advertising $7.5bn (2025) to $14.3bn (2030), 13.9% a year | WPP Media India, PwC India |
-
$3bn+
Saudi ad spend by 2027, and 91% of it digital by 2030
WARC via AGBI -
$2.7bn
UAE ad spend by 2027, with digital growing more than 10% a year
WARC via AGBI -
$5.5bn
GCC ad spend in 2027, even in a cautious scenario
WARC via AGBI -
$14.3bn
India internet advertising by 2030, up from $7.5bn
PwC India
Where is the money moving? Channel by channel, 2027 to 2031
The money is moving toward channels that sit close to a transaction or a screen people choose to watch: commerce media, streaming TV, digital out-of-home, gaming and AI-led search. Social stays the largest single channel at about $3.9bn in MENA in 2026, but its share is easing as these newer channels grow faster.
Growth in 2026 versus 2025. Streaming TV and commerce media grow three to five times faster than the market; WPP calls the out-of-home dip temporary.
Source: WPP Media, This Year Next Year, midyear 2026, via Communicate Online. Streaming TV size not published.
Commerce and retail media: the next big line item. Retailers, delivery apps and marketplaces sell ads next to the moment of purchase. MENA commerce media grew from $434m in 2025 and is forecast to pass $700m by 2028. IAB MENA measured retail media growth of up to 40.5% in 2025. WPP expects commerce media to overtake total TV in the region within about a year.
Streaming TV: where television is going. Streaming is forecast to take 55% of MENA TV ad revenue by 2030. Connected TV ad spend grew 31% in 2025 (IAB MENA). The big screen is becoming addressable, measurable and bought like digital.
Out-of-home: a dip, then a digital shift. OOH dips in 2026, which WPP calls temporary, while digital screens are forecast to make up 49% of MENA out-of-home by 2030, with programmatic DOOH budgets near $100m. Estimates of the total 2030 DOOH market range from $100m to $835m, so the direction is clearer than the size.
Gaming: a young market's media. Gaming ad spend is forecast at $213m in 2026, up 20%. With about 71% of Saudis under 35 (GASTAT) and the Esports World Cup returning to Riyadh from 16 July to 1 August 2027, gaming is a mainstream media channel, not a niche.
Search: from links to answers. Search makes up about 18% of MENA ad revenue in 2026. The generative part of it, ads and placements inside AI answers, is forecast to grow from 1% to 20% of that category by 2031. The next section covers what that means.
Ad tech and short video in Saudi Arabia. The Saudi ad-tech market is forecast to reach SAR 312m ($83m) by 2030, growing 20.7% a year, and short-form video ad spend SAR 477m ($127m) by 2028. More of the market will be bought through software and measured in real time.
How will AI search change brand discovery by 2031?
By 2031, being found will mean being the answer, not only a link on a results page. In the GCC today, Google still sends almost all search referral traffic: ChatGPT accounted for 0.43% of referral page views in the UAE and 0.39% in Saudi Arabia in September 2026. The change is happening inside Google itself, and it is quick.
- AI answers are now part of the results page. Google's AI Mode passed 1bn monthly users and the Gemini app 950m by mid-2026. ChatGPT reached about 1bn weekly users in July 2026.
- Fewer clicks when an answer appears. Pew Research found people clicked a result 8% of the time with an AI summary on the page versus 15% without one. Ahrefs measured the top result's click rate 58% lower when an AI Overview shows.
- The money follows. WPP Media forecasts generative search rising from 1% to 20% of MENA search-and-intelligence ad revenue by 2031. In the US, enterprises already put about 12% of digital budgets into GEO (Conductor via EMARKETER).
- The region adopts AI faster than almost anywhere. About 73% of the UAE's working-age population used AI in Q2 2026, the highest share in the world, against 31% in Saudi Arabia and 17.8% globally (Microsoft AI Diffusion Report).
Share of the working-age population using AI tools, second quarter of 2026. When three in four people ask an assistant first, the assistant’s answer is the new shop window.
Source: Microsoft AI Diffusion Report, via Enterprise AM.
-
1% → 20%
generative search’s share of MENA search ad revenue, 2026 to 2031
WPP Media -
8% vs 15%
how often people click a result when an AI summary appears, versus when it doesn’t
Pew Research -
1bn+
monthly users of Google’s AI Mode by mid-2026
Alphabet Q2 2026
SEO, AEO and GEO, in one line each:
| Discipline | The question it answers | What it needs |
|---|---|---|
| SEO (search engine optimisation) | Does my page rank? | Crawlable pages, links, relevance, speed |
| AEO (answer engine optimisation) | Is my page the answer that gets quoted? | Direct answers, question headings, FAQ and structured data |
| GEO (generative engine optimisation) | Does an AI model mention and recommend my brand? | Consistent facts about the brand across the web, citations by trusted sources, original data |
What will e-commerce in the GCC look like by 2030?
By 2030, GCC e-commerce will be faster, more social and almost cashless: the contest moves from whether people shop online to where, how fast and how they pay. Euromonitor forecasts MENA e-commerce growing from $126.7bn in 2024 to $212.2bn in 2029, and the UAE from $8.8bn to more than $13.8bn. Visa expects online to reach 46% of Saudi retail payments by 2030, up from 29% in 2024.
Pale bar: latest actual. Gradient bar: forecast. Each row is scaled to its own forecast.
Sources: Euromonitor via Economy Middle East; Visa via Arab News.
| Segment | 2030 forecast | Market | Source |
|---|---|---|---|
| Food delivery platforms | $26bn, up from $14bn in 2025 | GCC | Redseer |
| Quick retail (groceries and essentials) | $15bn | GCC | Redseer |
| Delivery market | SAR 40bn to 45bn | Saudi Arabia | Kearney |
| Buy now, pay later | $27bn to $53bn, up from about $8bn | Saudi Arabia | Redseer |
| Luxury | €30bn to €35bn | Middle East | BCG |
| E-retail | $170bn to $180bn | India | Bain |
| Quick commerce | $65bn to $70bn | India | Bain |
Five things the numbers say:
- Speed is the new shelf. Quick commerce and delivery are the fastest-growing parts of GCC retail. A brand that is not stocked, visible and advertised inside the delivery apps will be missing from the moment people decide.
- Payment is part of the marketing. E-payments already made up 85% of Saudi retail payments in 2025 (SAMA), and 70% of shoppers say they avoid retailers that do not offer flexible payment (Tabby). How a customer can pay is now a reason to choose a store.
- Social becomes a checkout. 86% of UAE shoppers already buy through social platforms, and 96% expect most of their online purchases to happen there by 2030 (DHL). In Ramadan, 61% shop through Instagram or TikTok (YouGov).
- Stores close sales that started online. 77% of product discovery is digital and 68% of shoppers know what they will buy before they walk in (Tabby). Physical retail stays strong; Emaar's malls run at 98% occupancy. Online media decides; the store completes.
- The phone is the store. The UAE ranks first in the world for smartphone shopping, with 67% buying on a phone (PYMNTS). Every journey in this outlook is mobile first.
How are AI assistants and agents changing how people buy?
AI is moving from helping people choose to choosing for them, and GCC shoppers are ahead of the curve. The agentic part, where software compares, books and pays, is the 2027 to 2030 story.
-
85%
of UAE shoppers have used AI to shop; 32% would let an agent check out for them
Visa -
43% / 30%
of Saudi and UAE shoppers use AI to decide what to buy, and fully trust it
Tabby -
$15tn
of B2B purchases handled by AI agents by 2028
Gartner -
84% / 11%
of GCC organisations use AI, and get significant value from it
McKinsey
Consumers (B2C):
- In the UAE, 85% of shoppers have used AI to shop, 60% use it to check reviews, and 32% would let an AI agent complete a checkout (Visa).
- Across Saudi Arabia and the UAE, 43% use AI to decide what to buy, but only 30% fully trust it (Tabby, more than 20,000 shoppers). Adoption is running ahead of trust.
- In Saudi Arabia, 66% of consumers now use AI tools, up from 49% (Deloitte, 2026).
Businesses (B2B):
- Gartner forecasts that by 2028 AI agents will handle more than $15tn of B2B purchases.
- 61% of B2B buyers prefer to buy without talking to a sales rep, and 73% avoid suppliers who send irrelevant outreach (Gartner).
- 84% of GCC organisations use AI, up from 62% in 2023, but only 11% get significant value from it (McKinsey). Among UAE and Saudi marketers, 96% have tried AI but 26% use it regularly (Ipsos MENA).
The national bets behind it: PwC estimates AI could be worth 12.4% of Saudi GDP ($135.2bn) and about 14% of UAE GDP by 2030. The UAE National AI Strategy 2031 and Saudi Arabia's data and AI strategy set national targets to 2030 and 2031, and the UAE strategy names customer service as one of its objectives.
What happens to creators, influencers and podcasts by 2030?
Creators become a regulated, professional media channel, and long-form audio becomes one of the few places a brand can hold attention for 30 minutes. Globally, Goldman Sachs expects the creator economy to grow from about $250bn to $480bn by 2027.
Podcast advertising grows fastest of the three: about five times its 2025 size by 2034.
Sources: Goldman Sachs; Kolsquare; IMARC.
Creators and influencers:
- GCC influencer marketing is forecast to grow from $315.5m in 2025 to $771.6m by 2032, about 13.9% a year. UAE influencer spend alone is forecast at $97m by 2030.
- Licensing is now standard. The UAE Media Council's advertiser permit is mandatory and free for the first three years, and Saudi Arabia's Mawthooq licence also applies to visiting influencers.
- Snapchat counts more than 1.4m creators in MENA and reaches over 90% of Saudis aged 13 to 34.
- The 1 Billion Followers Summit runs in Dubai from 8 to 10 January 2027, with Creators HQ at about 5,000 approved members.
- Forrester expects 75% of enterprises to raise influencer budgets in B2B too: creators are not only for consumer brands.
Podcasts and audio:
- Weekly podcast listening reaches 67% in Saudi Arabia and 57% in the UAE, and monthly listeners across the Middle East and Africa grew 21.2% in 2025.
- GCC podcast advertising is forecast to grow from $309.8m in 2025 to $1.56bn by 2034, about 19.1% a year. For scale, US podcast ad revenue is forecast at about $2.6bn in 2026 (IAB).
Why do CRM, WhatsApp, ABM and first-party data matter more every year?
As discovery spreads across feeds, apps and AI answers, the customer relationship a brand owns becomes its most stable asset. Four trends point the same way.
-
65% vs 48%
of UAE residents contacted a business on WhatsApp in a year, versus by email
Communicate Online -
$9.33bn
Middle East and Africa CRM market by 2033, from $4.34bn in 2025
Grand View Research -
95%
of B2B buyers are not in the market at any given moment
LinkedIn B2B Institute -
71%
of B2B practitioners now use account-based marketing
Demand Gen Report
1. The conversation lives in WhatsApp. In the UAE, 65% of residents contacted a business on WhatsApp in a year, against 48% by email, 85% want every business to offer it, and 87% prefer a human to a bot. Business messaging grew 53% in 2025, with the UAE the largest market in EMEA in that study. The winning model through 2030 is automation for speed and routing, with a person for the conversation.
2. CRM and automation keep compounding. The Middle East and Africa CRM market is forecast to grow from $4.34bn in 2025 to $9.33bn by 2033, and marketing automation in the wider Middle East to about $671m by 2030, 14.3% a year. Most teams already own these tools; the value is in connecting them so every lead gets a fast, relevant follow-up.
3. Consent is enforced. Saudi Arabia's Personal Data Protection Law has been enforceable since September 2024, with 48 enforcement decisions by January 2026 and fines of up to SAR 5m. Many cases involved marketing messages sent without consent. Opt-in lists, clear preferences and easy unsubscribes are now a growth requirement, not paperwork.
4. B2B buyers decide before they talk. At any moment, about 95% of B2B buyers are not in the market (LinkedIn B2B Institute). 71% of B2B practitioners now use account-based marketing, and their top challenge is proving ROI (Demand Gen Report).
The 2027 to 2034 demand calendar
The GCC calendar is getting denser and earlier. Ramadan moves about 11 days earlier every year, so by 2030 it will fall in early January, and 2030 will have two Ramadans: one starting around 5 January and one around 26 December. Q1 campaigns, winter sales and Ramadan planning will increasingly overlap.
Each bar is the expected month of Ramadan, December to March. By 2030 there are two: one in early January and one starting in late December.
Astronomical estimates (UAE Astronomy Centre for 2027; FCNA calculations for 2028 to 2030), within one or two days. Events from the AFC and the 2027 F1 calendar.
January to March 2027 is the busiest stretch of the decade before the World Cup. The AFC Asian Cup runs in Riyadh, Jeddah and Al Khobar from 7 January to 5 February, Ramadan follows from around 8 February (Khaleej Times), and the Saudi Grand Prix is on 21 March. Ramadan spend also concentrates late: in Saudi Arabia, pre-Ramadan spend rose 34.7% to $4.6bn and the peak hours run from 10pm to 2am (Tamara).
| Anchor event | Dates | Where | Why it matters |
|---|---|---|---|
| Esports World Cup | 16 Jul to 1 Aug 2027 | Riyadh | Gaming and youth audiences in summer |
| Abu Dhabi Grand Prix | 12 Dec 2027 | Abu Dhabi | Season finale, premium audiences |
| Expo 2030 Riyadh | 1 Oct 2030 to 31 Mar 2031 | Riyadh | Six months of global visitors |
| FIFA World Cup | 2034, dates to be confirmed | Saudi Arabia | 48 teams, 104 matches |
Tourism, sport and property are the demand engines:
- Saudi Arabia welcomed more than 122m visitors in 2025, spending about SAR 300bn, and targets 150m visitors a year by 2030. Domestic travel is the steady base: it grew 16% in Q1 2026.
- Dubai hosted a record 19.59m international overnight visitors in 2025, and the D33 agenda aims to double the size of Dubai's economy by 2033.
- The Saudi sports market is forecast to grow from about $8.5bn to $22.4bn by 2030.
- Dubai real estate recorded AED 917bn of transactions in 2025, toward an AED 1tn target for 2033, and AED 286.4bn in H1 2026. In Saudi Arabia, home ownership passed 66% in 2025 against a 70% target for 2030, and about half of one major developer's sales are already made digitally.
What should brands do in 2027? A playbook by discipline
The common thread is simple: be easy to find, easy to trust and easy to buy from, in every place the customer now decides. Here is what that means for each discipline.
| Discipline | The 2027 to 2031 shift | What to do in 2027 |
|---|---|---|
| Go-to-market strategy | A rebound year after a disrupted 2026, with Saudi Arabia leading growth | Set one plan for the UAE, Saudi Arabia and India, each with its own audience, channel mix and calendar. Phase budgets by quarter and keep a reserve for event changes. |
| Search, AEO and GEO | Generative search grows from 1% to 20% of search-and-intelligence ad revenue by 2031 | Rewrite key pages to answer one question each, add FAQs and structured data, publish original numbers, and keep brand facts consistent everywhere AI reads them. |
| Commerce and retail media | MENA commerce media above $700m by 2028 | Treat delivery apps, marketplaces and retailer sites as media. Fix product listings and content first, then advertise where the purchase happens. |
| Social and creators | GCC influencer spend reaching $771.6m by 2032; 96% of UAE shoppers expecting to buy mostly through social by 2030 | Fewer, longer creator partnerships with licensed creators, clear briefs and shoppable content. Plan Arabic and English content separately, not as translations. |
| Thought-leadership podcasts | Weekly listening at 67% in Saudi Arabia and 57% in the UAE | Launch a focused show that teaches the buyer something each episode, and cut it into short clips for social and email. |
| CRM, ABM and automation | Consent enforced in Saudi Arabia; WhatsApp is the region's business inbox; B2B buyers research alone | Clean the CRM, build consented WhatsApp and email journeys with a person on hand, and run ABM on a short list of named accounts with content that is useful before they buy. |
| AI in marketing operations | 84% of GCC firms use AI; 11% get significant value | Pick three workflows (briefs, content variants, reporting), set rules and training, and measure time saved and quality. |
| Streaming TV and digital out-of-home | Streaming 55% of MENA TV ad revenue by 2030; digital 49% of OOH | Test streaming TV and digital screens for reach, and judge them on brand search and site visits that follow. |
| Seasonal planning | Ramadan moving into January by 2030; a dense Q1 2027 | Lock Q1 media and creators early, plan for late-night Ramadan peaks, and merge Ramadan and winter-season planning from 2028. |
| E-commerce and payments | Flexible payment expected by 70% of shoppers | Show delivery speed and payment options in the ad itself, and make the path from ad to checkout as short as possible. |
A good first step for any brand is an honest audit of where it already leaks attention, leads or sales between these channels. Fixing those leaks usually pays for the next stage of growth.
Frequently asked questions
How big is the MENA advertising market in 2027?
WPP Media forecasts MENA ad spend at $8.4bn in 2026, and broader estimates put the region near $11bn, growing 7 to 9% a year to 2030. WARC forecasts Saudi Arabia above $3bn and the UAE at $2.7bn in 2027.
What share of Saudi advertising will be digital by 2030?
About 90% by 2029 and 91% by 2030, according to Gmedia and Oxford Business Group.
What is the fastest-growing ad channel in MENA?
Streaming TV (+38.3% in 2026) and commerce and retail media (+22.2% to $636m in 2026) grow fastest, according to WPP Media. Commerce media is forecast to pass $700m by 2028.
What is GEO, and why does it matter in the GCC?
GEO, or generative engine optimisation, is the work of getting a brand mentioned and recommended in AI answers from tools like Google's AI Mode, Gemini and ChatGPT. It matters because the UAE has the world's highest AI adoption, at about 73% of working-age people, and because clicks fall when AI summaries appear.
When is Ramadan in 2027, 2028, 2029 and 2030?
Ramadan is expected to start around 8 February 2027, 28 January 2028, 16 January 2029 and 5 January 2030, with a second Ramadan starting around 26 December 2030. Dates depend on the moon sighting and can move by a day or two.
Do influencers need a licence in the UAE and Saudi Arabia?
Yes. The UAE requires an advertiser permit from the UAE Media Council, free for the first three years. Saudi Arabia requires a Mawthooq licence, including for visiting influencers.
Is WhatsApp marketing allowed in Saudi Arabia?
Yes, with consent. Saudi Arabia's Personal Data Protection Law is enforced, with fines of up to SAR 5m, and many cases involve marketing messages sent without consent.
Which events will shape GCC marketing calendars from 2027 to 2034?
The AFC Asian Cup (January to February 2027), the Esports World Cup in Riyadh (July 2027), Expo 2030 Riyadh (October 2030 to March 2031) and the FIFA World Cup in Saudi Arabia in 2034.
Methodology and sources
This outlook brings together published forecasts from media agencies, consultancies, regulators, multilaterals and platforms, checked on 13 October 2026. Every page cited was opened and read; figures come from the page, not from search summaries. Where publishers disagree, we name the series and do not mix them. Forecasts made before 2026 are labelled with their publication year, and figures from market-research vendors or interested parties are treated as directional.
Ad spend and media: WPP Media MENA midyear 2026 · WPP Media MENA 2025 forecast · IAB MENA Adex 2025 · WARC via AGBI, 2025 · WARC via AGBI, 2026 · Gmedia / OBG · PwC Strategy& MENA Media Outlook · PwC India E&M Outlook
E-commerce and payments: Euromonitor via Economy Middle East · Visa via Arab News · SAMA · Redseer, GCC delivery · Redseer via AGBI, quick commerce · Redseer via Arabian Business, BNPL · Kearney · Tabby shopping survey 2026 · DHL via Arabian Business · BCG luxury · Bain, How India Shops Online 2026 · PYMNTS via bne IntelliNews
AI, search and B2B: Pew Research · Ahrefs · Alphabet Q2 2026 · Statcounter · Microsoft AI Diffusion Report · McKinsey, State of AI in the GCC · Ipsos MENA · PwC AI in the Middle East · Gartner B2B buying · Gartner AI agents · Forrester 2026 predictions · Deloitte KSA 2026 · Visa and Checkout.com via Gulf Business
Creators, podcasts, CRM and privacy: Goldman Sachs · UAE advertiser permit · Mawthooq · Snap via AGBI · Next Audio via Campaign ME · IMARC · Zbooni / YouGov · Saudi PDPL enforcement · Grand View Research CRM · MarketsandMarkets
Economy, events and demand: World Bank, October 2026 · UAE Central Bank · Saudi tourism 2025 · Dubai tourism 2025 · Dubai Land Department · Saudi sports market · BIE, Expo 2030 · FIFA · F1 2027 calendar · Ramadan 2027 dates · Ramadan 2030 dates